Banking Resume Examples
Your profile should state your years on the line, the bank type you have worked in (national bank, regional, community bank, credit union, private bank), and the products that fill your day. Name whether you…
Household deposit growth tied to real dollar figures, referral volume to mortgage or wealth partners, and NMLS registration listed near the top are what separate the Personal Banker resumes branch managers advance from the rest.
An entry-level personal banker resume has to show teller or retail service work and comfort with cash handling. Prove you can open deposit accounts, refer customers to lending, and study for the SIE or NMLS registration.
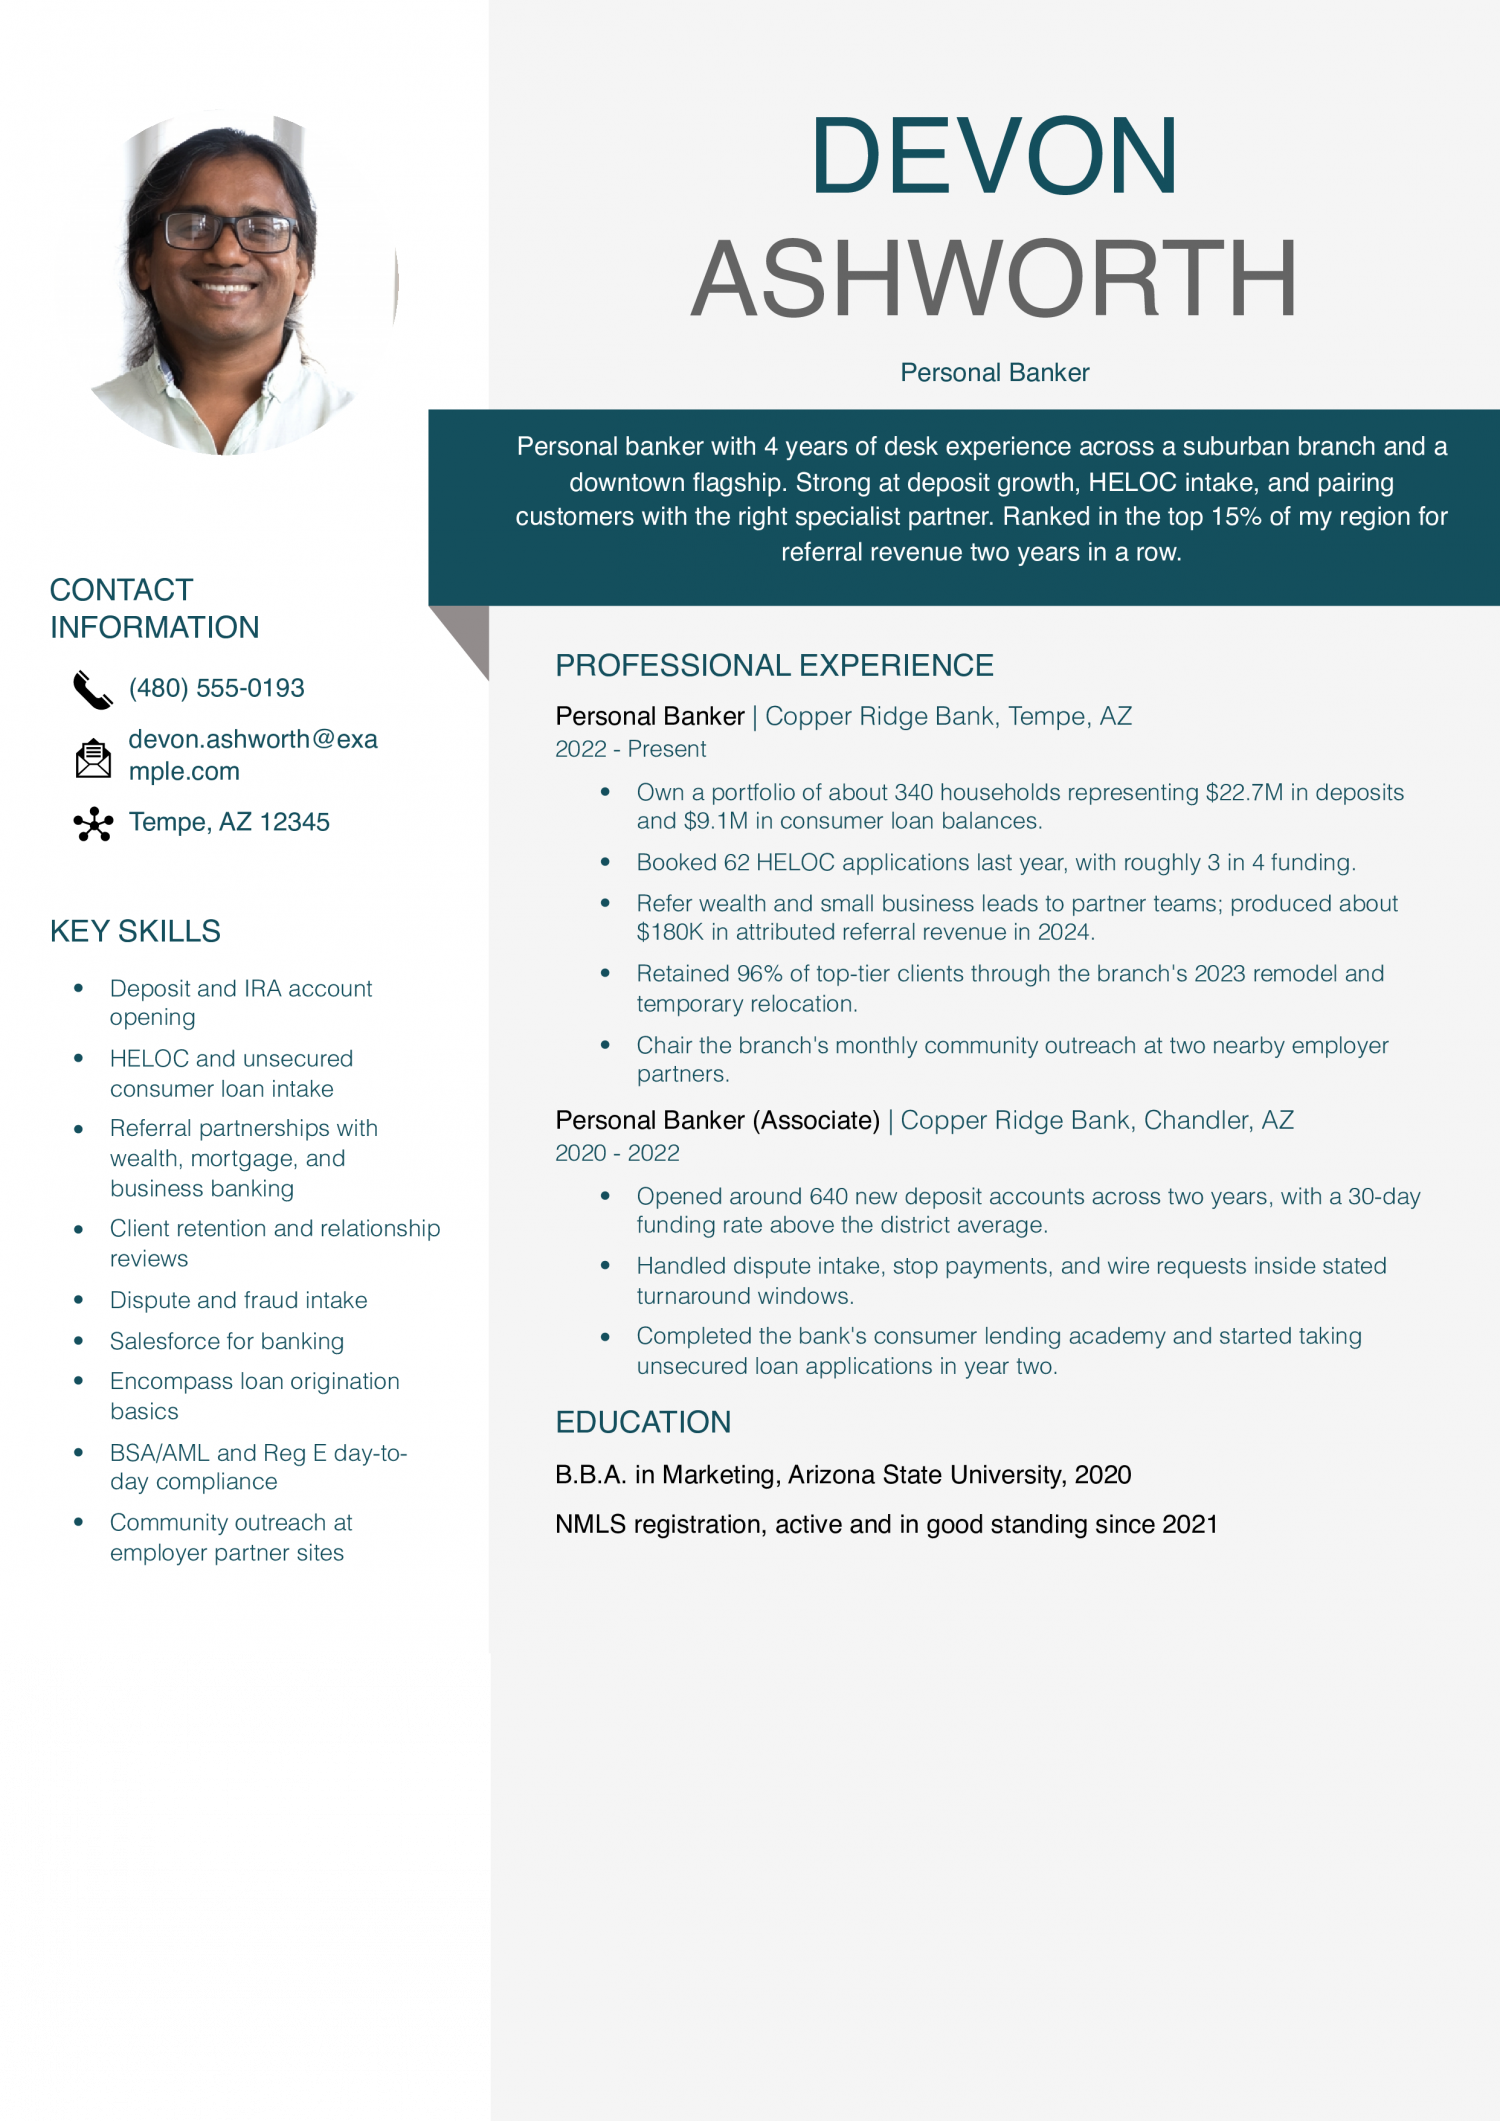
An experienced personal banker resume should show a steady book of deposits and referrals sent to mortgage partners. Branch managers want to see growth in balances, cross-sell ratios, and loans you close on your own.
A senior personal banker resume must show you own the branch's top households and coach new bankers. Show mortgage referral revenue, how you keep high-balance clients, and your part in branch sales goals.
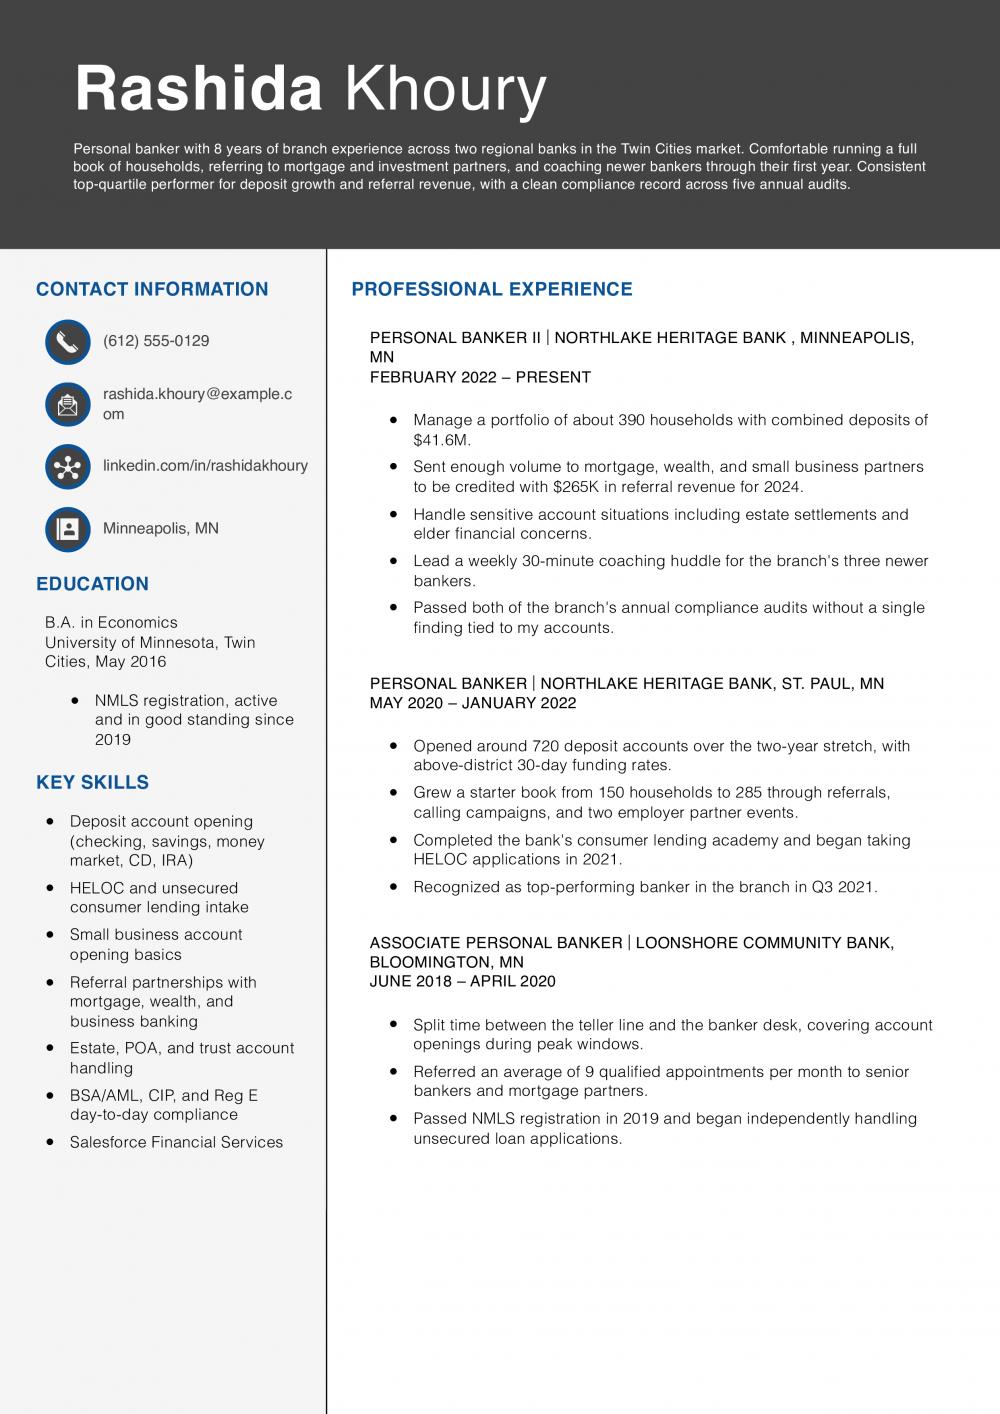
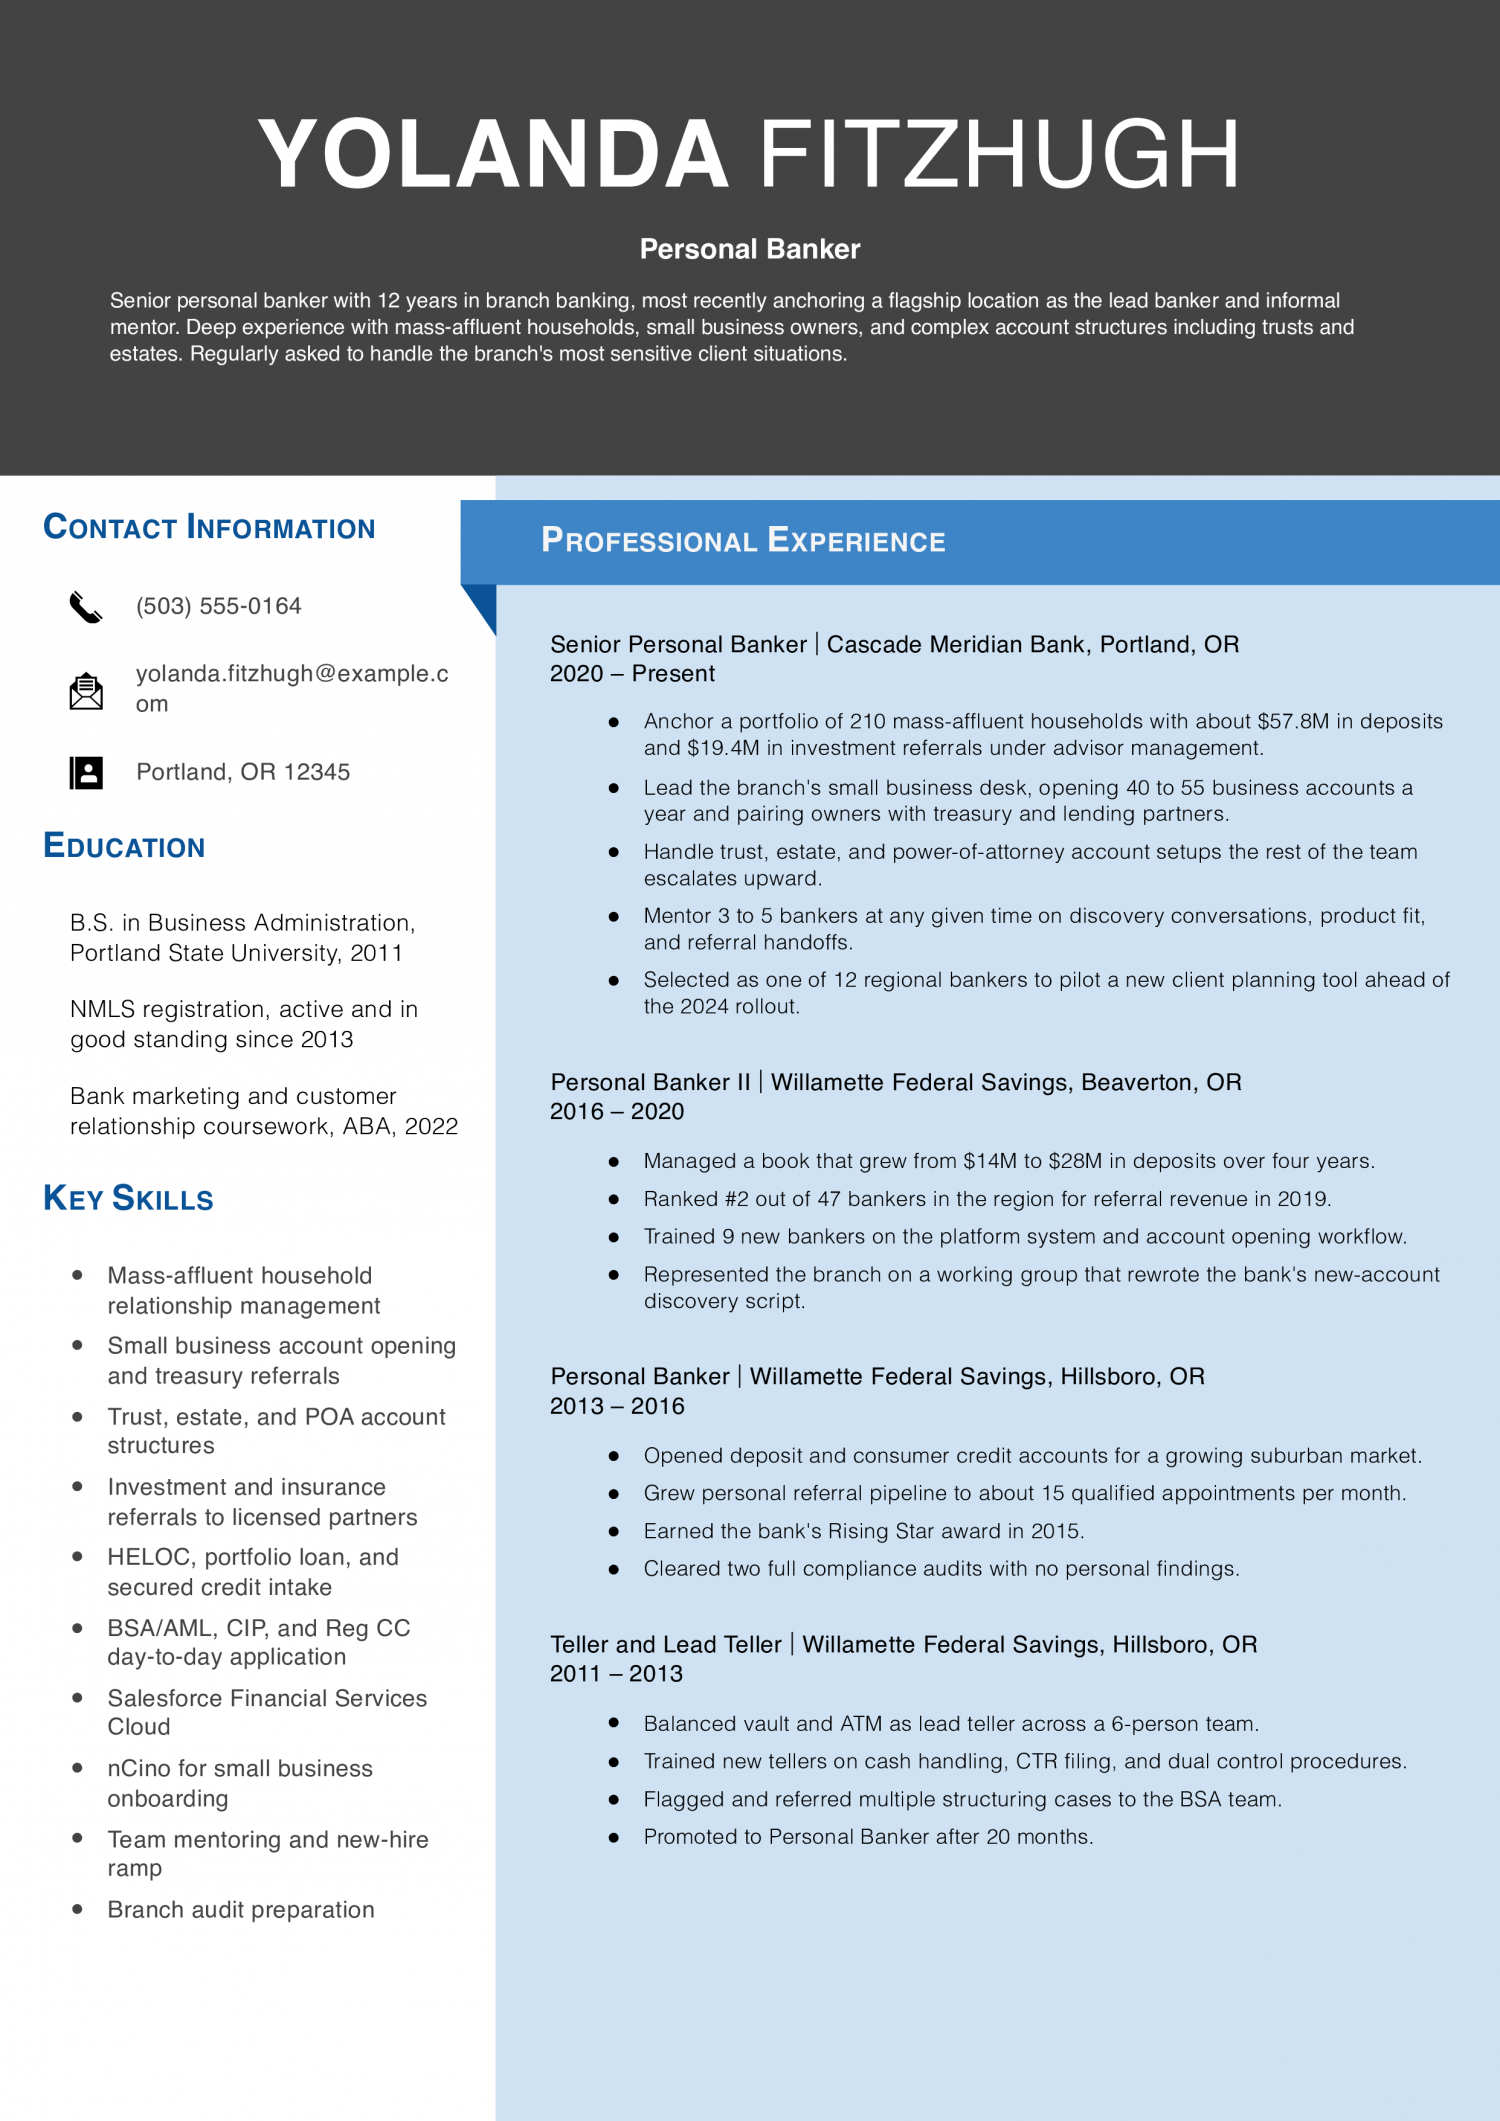
Rashida Khoury
Minneapolis, MN | (612) 555-0129 | [email protected] | linkedin.com/in/rashidakhoury
Personal banker with 8 years of branch experience across two regional banks in the Twin Cities market. Comfortable running a full book of households, referring to mortgage and investment partners, and coaching newer bankers through their first year. Consistent top-quartile performer for deposit growth and referral revenue, with a clean compliance record across five annual audits.
Personal Banker II
Northlake Heritage Bank | Minneapolis, MN | 2022-Present
Personal Banker
Northlake Heritage Bank | St. Paul, MN | 2020-2022
Associate Personal Banker
Loonshore Community Bank | Bloomington, MN | 2018-2020
Teller
Loonshore Community Bank | Bloomington, MN | 2016-2018
Lead with one signal a branch manager cannot pull from a registry check. Name your NMLS registration if you hold it, then add the edge next to it. That edge might be a Spanish or Mandarin book of business.
It might be small business deposit growth in a specific market. It might be a wealth referral pipeline you built with a licensed partner. A generic summary reads like every other applicant in the stack.
A first line that names your book, your language, or your referral partner does not. Put this line at the top of the summary. Keep it to one sentence so recruiters see it in the first scan.
Personal banking is a numbers seat, so recruiters scan for figures first. A bullet with no number reads as a task you did, not a result you drove. Name two or three metrics per role and keep them realistic.
Strong bullets cite deposit growth in dollars or percent over a stated period. They cite referrals sent to mortgage or wealth partners per month. They cite consumer loan volume closed or households deepened.
Include your branch size or portfolio size so the numbers have context. A 15 percent deposit lift means one thing at a small branch. It means another at a flagship.
If you cannot cite dollars, cite volume: accounts opened, appointments held, or reviews completed each week.
Split your bullets so a reader sees the full scope in one pass. Use four buckets and keep each to two or three lines. Client acquisition covers outbound calls, appointment setting, and lobby engagement.
Financial reviews cover needs analysis, product recommendations, and household deepening. Lending covers consumer loans, credit cards, and home equity applications. Referrals cover warm handoffs to mortgage originators and wealth advisors.
Compliance work sits under each bucket where it fits, not in its own pile. Name the core systems in line with the work. Examples include your bank’s CRM, teller platform, or loan origination system.
A grouped layout reads faster than a run of mixed duties.
Put licenses and registrations in a credentials block on page one, under your summary. Branch managers and retail-banking recruiters check for these before they read bullets. List your NMLS Mortgage Loan Originator Registration with the federal registry named.
List the Securities Industry Essentials Exam from FINRA if you have passed it. List the ABA Personal Banker Certificate from ABA if you hold it. Show state and status as license in good standing.
Do not publish your NMLS ID number on the resume itself. Name the platforms you use in a short tools line: your CRM, your loan origination system, and your core banking system. Rules vary by employer and state, so match the posting when you decide what to feature.
End the resume with a short education section and a training line. List your degree, school, and graduation year if you finished within the last ten years. Older graduates can drop the year and keep the degree.
Add a continuing education line under education for bank-sponsored training. Examples include Bank Secrecy Act refreshers, sales coaching cohorts, or product certifications from your employer. Keep each entry to one line so the section stays tight.
Do not repeat licenses here that already sit in your page-one credentials block. If you are early in your career, move education above work history. If you have three or more years in seat, work history stays first and education closes the page.
Five years ago, a Personal Banker resume read like a teller job card with product names listed under it. The mix has shifted toward household growth, referral counts to mortgage and wealth partners, and NMLS registration on the header. Branch managers and retail-banking recruiters read the hard skills first to confirm you can run the book.
Soft skills like client discovery back up the bullets that show the work. Run the two tables below against the posting you want. Keep only the terms that match your real work at the teller line or platform desk.
Drop any phrase you cannot back with a bullet showing a number or a named product. Add the posting’s exact wording where your term is close but not the same. A branch that says consumer lending will not credit you for loan origination on a first scan.
Move the terms you keep into the summary, the skills block, and at least one bullet each. That mirroring is what carries a resume past the ATS and onto the branch manager’s screen for a real read.
| Soft Skills | AI-estimated % |
|---|---|
| Client rapport building | 74% |
| Active listening | 52% |
| Cross-selling awareness | 41% |
| Detail orientation | 35% |
| Needs-based referrals | 28% |
And here are the top hard skills showing up most often.
| Hard Skills | AI-estimated % |
|---|---|
| New account opening | 68% |
| Customer deposit processing | 62% |
| Financial product explanation | 41% |
| Account error resolution | 37% |
| Regulatory compliance documentation | 33% |
Skill names and rankings come from an AI model grounded in U.S. Department of Labor occupation data for personal bankers, not from a count of personal bankers’ resumes built on ResumeTemplates.com.
Before a personal banker resume gets a closer read, hiring teams check for a short list of essentials.
Branch managers and retail-banking recruiters scan for the work you actually did. The rows below map the main lanes of personal banker work. Deposits cover new accounts, CDs, and money market moves. Lending covers consumer loans, HELOC files, and mortgage handoffs. Compliance covers the daily rules that keep a branch clean. Referrals cover the growth side that pays out on your scorecard. Service covers the front-line work at the teller line and desk. Pick the rows that match your book of business. Mirror the exact spelling from your job posting. Keep credentials, systems, and rules in their trade capitals. Drop these terms into your bullets where the work is real.
| Niche | Keywords ATS scans for |
|---|---|
| Deposit products | new account opening, CD renewals, money market accounts |
| Consumer lending | HELOC origination, unsecured loans, auto loan referrals |
| Compliance and risk | BSA and AML, KYC verification, CIP review |
| Cross-sell and referrals | wealth referrals, mortgage handoffs, small business leads |
| Branch service | cash handling, wire transfers, dispute resolution |
AI use on a personal banker resume can go three ways. You can lead with a puffed line like ‘AI-driven client advisor,’ which recruiters screen out fast. You can leave it off and answer the question in the interview room. Or you can describe the workflow as it actually runs at the branch. The third is what branch managers and retail-banking recruiters can validate. Name the tool, name the task, and name who reviews the output before it reaches a client. Bank AI use sits inside vendor rules, model risk review, and privacy law. Anything you claim has to survive that check.
Bank CRMs now score which households to call for deposit growth, loan renewals, or referral conversations.
Assistants summarize prior contact notes and product holdings before a scheduled review with a client.
Rules-based tools pre-screen consumer loan and card applications before you hand them to underwriting.
Transaction monitoring surfaces suspicious activity you must review, document, and escalate under bank policy.
Beyond the state and federal registrations your branch already requires you to hold, the credentials below tell branch managers and retail-banking recruiters which parts of the book you are ready to work. Some signal you can move past deposits into investment referrals. Others show you can take a mortgage application at the desk without a handoff. A short entry-level certificate signals you have the core product and service training in place. List each item with its issuing body and the month and year you earned or registered it. If a credential has an expiration or a renewal date, put that on the same line.
The Bureau of Labor Statistics does not publish a wage code for Personal Banker specifically. The numbers below are a proxy: the closest published match is New Accounts Clerks (SOC 43-4141), so use them as an estimate for this role, not an exact figure.
Personal Banker is a narrow role in the BLS wage record. Supply is thin, so a specific credential reads as real proof to branch managers and retail-banking recruiters. The spread from the tenth to the ninetieth percentile is wide for a role this size.
The same job title covers a teller-adjacent floor and a licensed-referral ceiling. The top decile sits well above the middle of the band. The bottom decile trails the median by a fair margin.
That gap is where your resume does its work. Aim for a rung by leading with the licenses you carry and the referral partners you feed, not the transactions you process.
| # | State | Median Annual |
|---|---|---|
| 1 | District of Columbia | $60,990 |
| 2 | North Dakota | $57,970 |
| 3 | New York | $57,950 |
| 4 | New Jersey | $57,240 |
| 5 | Connecticut | $57,080 |
| 6 | Washington | $52,830 |
| 7 | California | $52,100 |
| 8 | New Mexico | $51,380 |
| 9 | Missouri | $50,270 |
| 10 | Tennessee | $49,770 |
| # | State | Workers | Median |
|---|---|---|---|
| 1 | New York | 4,800 | $57,950 |
| 2 | Texas | 2,360 | $44,040 |
| 3 | Wisconsin | 2,100 | $48,050 |
| 4 | Illinois | 2,020 | $49,040 |
| 5 | North Carolina | 1,910 | $49,480 |
Resume Templates offers HR approved resume templates to help you create a professional resume in minutes. Choose from several template options and even pre-populate a resume from your profile.
Mirror the posting first, then work in deposit growth, cross-sell ratio, and referral pipeline.
Add product terms the bank sells, such as consumer loans, home equity lines, and treasury basics. Name your core system by product, like Fiserv DNA or Jack Henry SilverLake, not just "core banking."
Reframe teller bullets around referrals made, appointments booked, and product conversations, not transactions counted.
Show the moment you began opening accounts, closing consumer loans, or handing warm referrals to mortgage partners. Branch managers and retail-banking recruiters read that shift as the readiness signal they need.
Yes, name the portfolio size in dollars and the household count you owned end to end.
A line like "managed a $42M consumer deposit book across 380 households" beats any adjective. If your bank treats those figures as confidential, round to the nearest five million and say so.
Keep the reverse chronological order and label the gap in one short line under your last role.
Say what you did during it, such as caregiving, contract teller shifts, or SIE study through Kaplan. Branch managers and retail-banking recruiters penalize hidden gaps more than named ones.
Put compliance in the context of a result, not as its own section of rules.
Write "opened 220 accounts with zero KYC exceptions in 2023" rather than listing BSA, CIP, and Regulation CC. One clean audit line tells a recruiter more than a paragraph of acronyms.
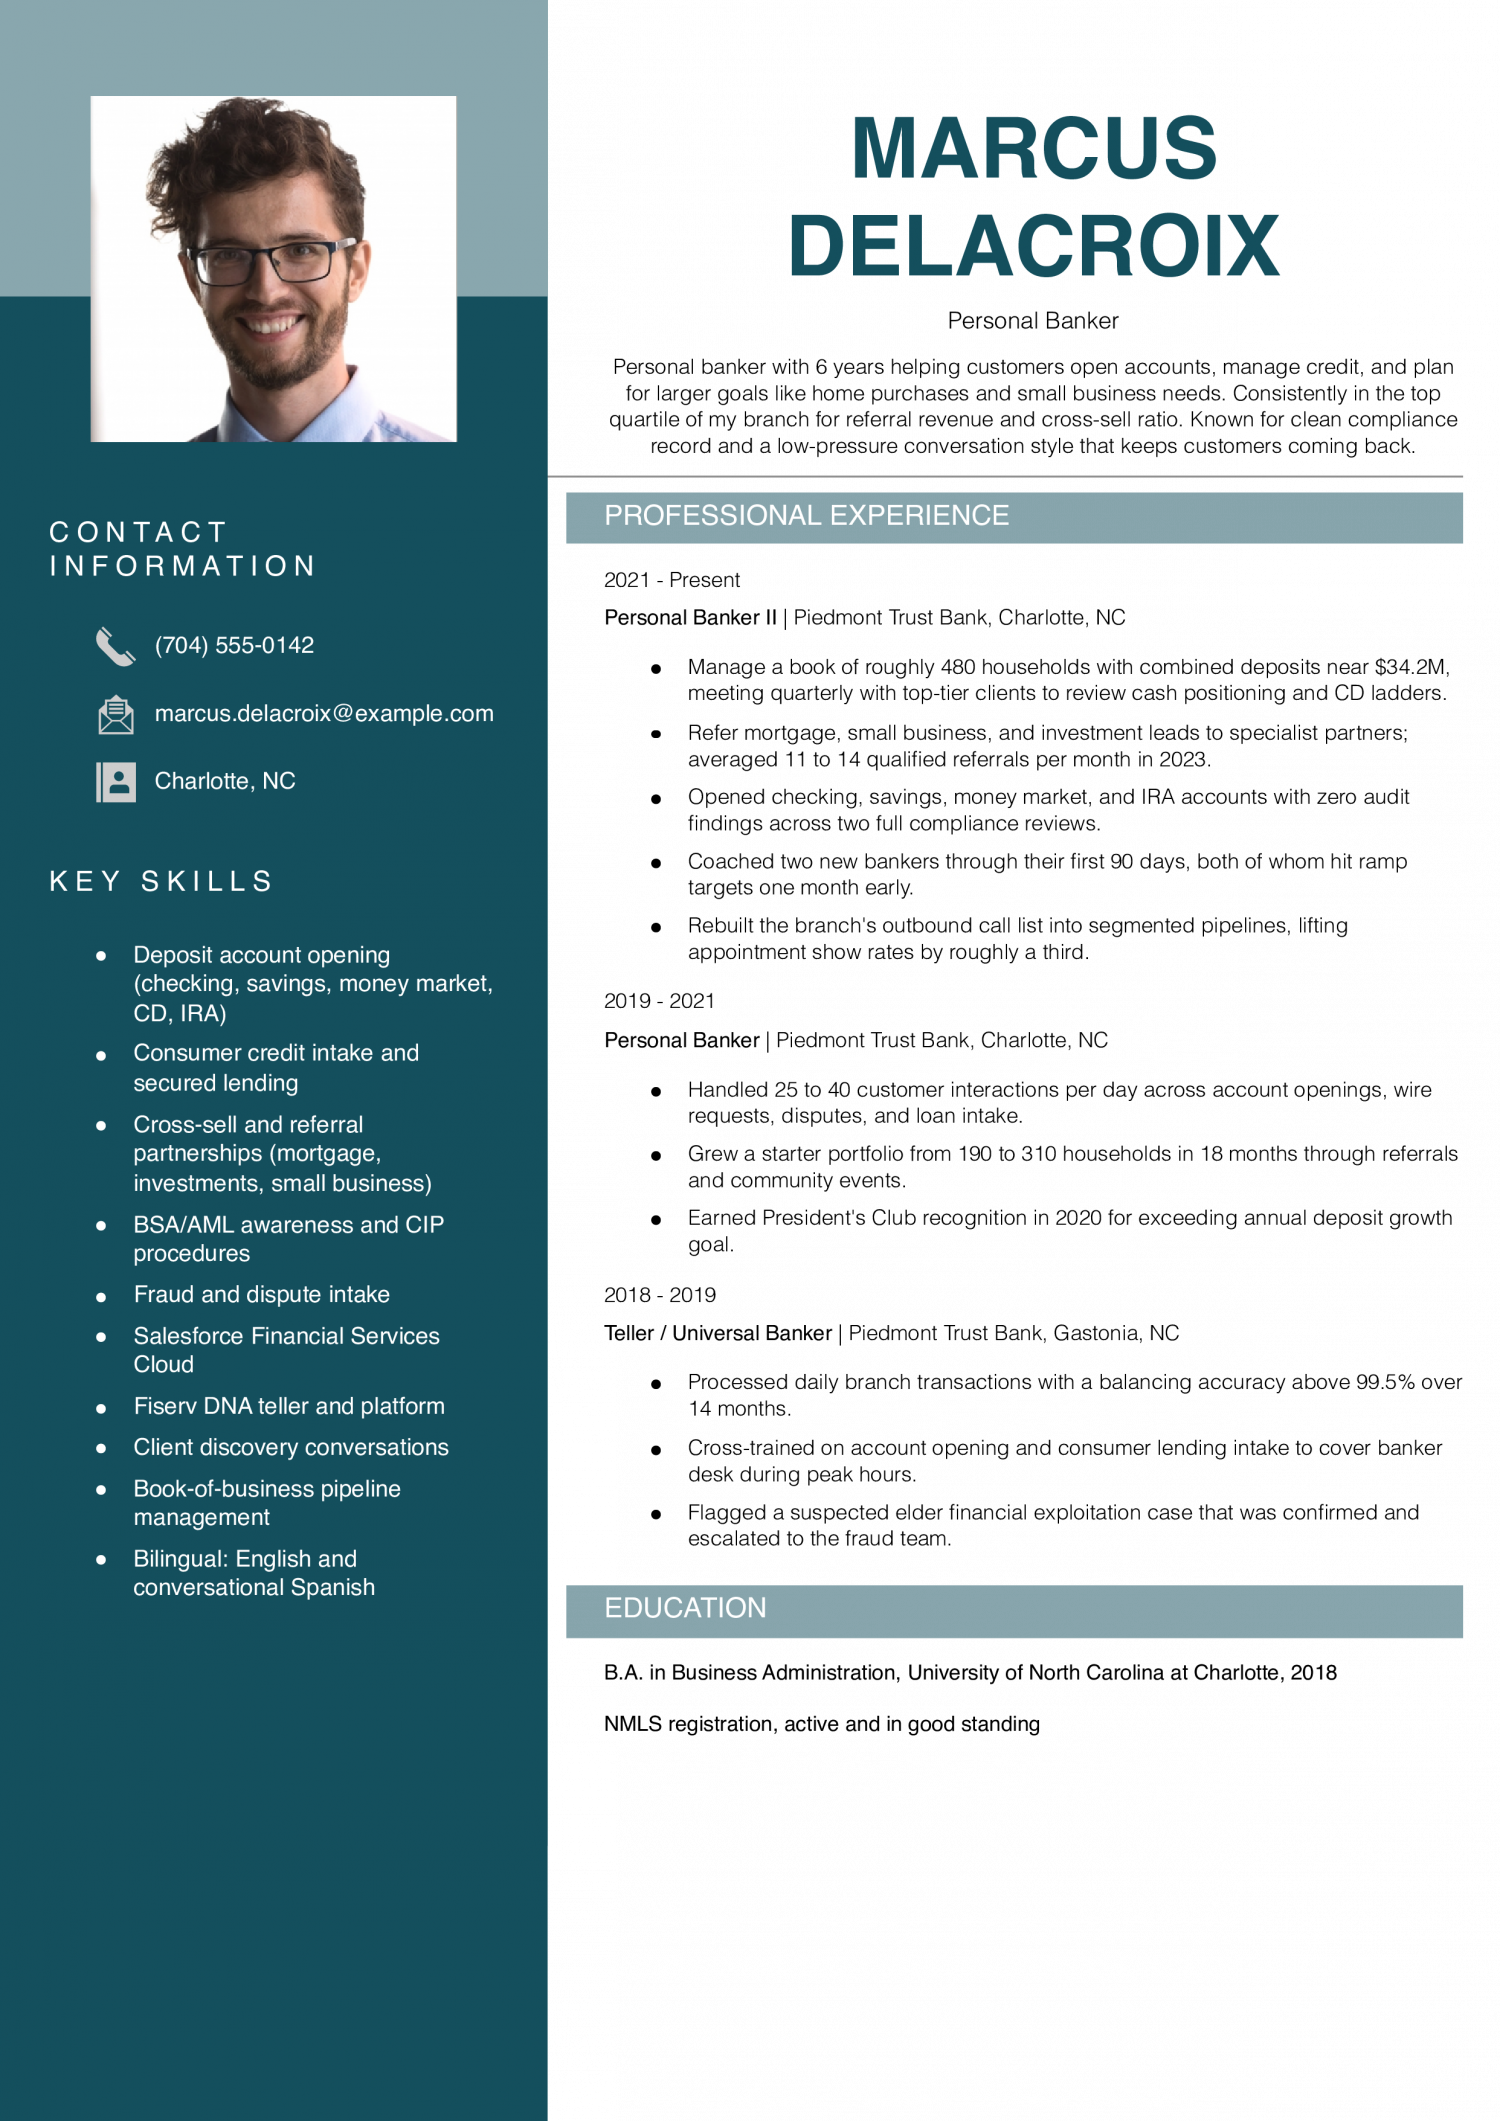
Write a three-line summary that names your years in retail banking, book size, and product focus.
Skip it only if you are a current teller with under two years and no book to point at. In that case, lead with a skills band and let the experience section carry the story.
Two different credentials sit under the NMLS umbrella, so label them separately on the resume.
List the federal registration as "NMLS Mortgage Loan Originator Registration, in good standing" with no state attached. List any state loan originator license on its own line with the state and status, such as "Ohio MLO license, active."
For a personal banker, an ATS-friendly template is the safest pick, because it puts your certifications and experience where a hiring manager scans first. A basic template is a solid alternative. Whichever you choose, keep the formatting clean and easy to parse: clear section headings, a standard font, and no graphics a parser can choke on.